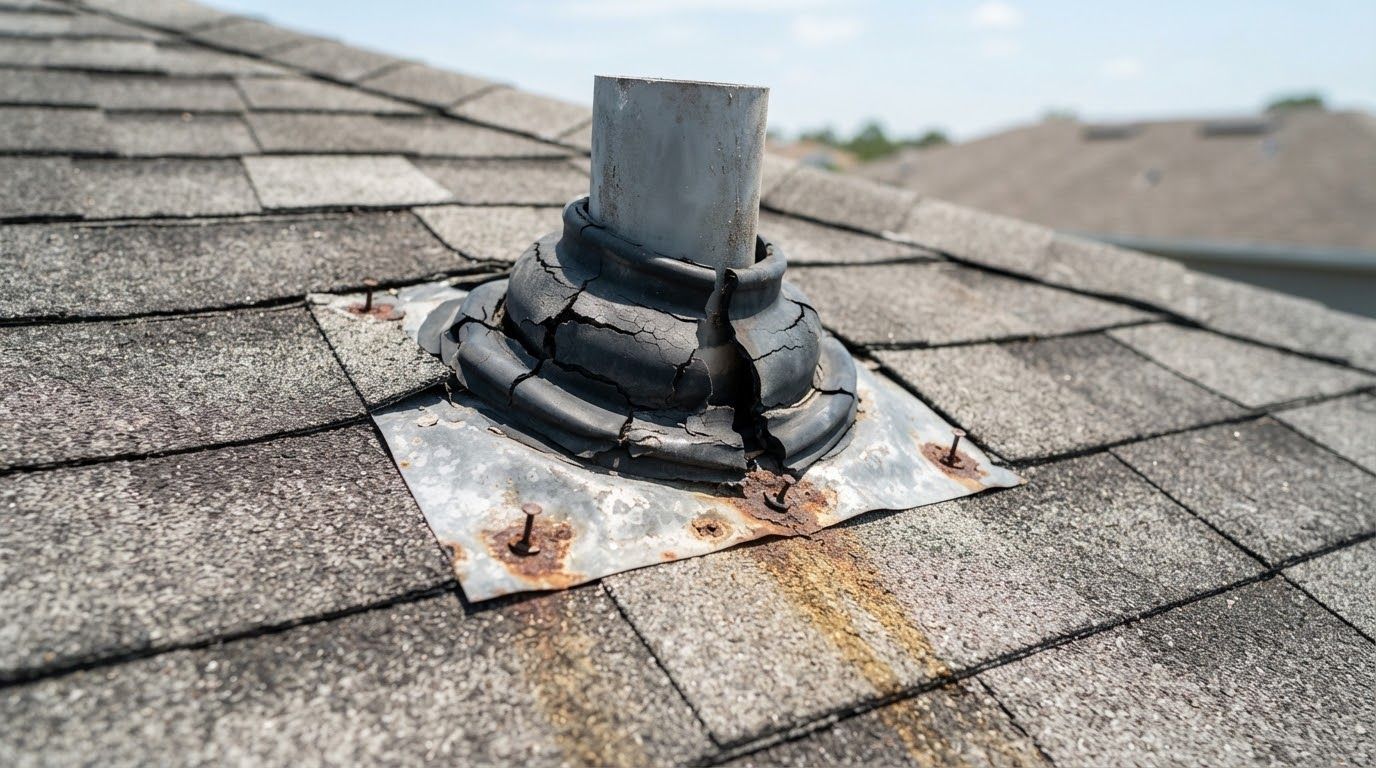
What the VA appraiser checks on the roof
A VA appraiser doesn’t certify the roof. They check it against VA’s Minimum Property Requirements, which say the roof covering must keep moisture out and provide reasonable future utility, durability and economy of maintenance. A roof that falls short shows up as a repair item on the appraisal, and the lender decides what it takes to clear it.
Licensed, insured roofers handle VA appraisal roof repairs for buyers and sellers across Hillsborough County. Call Roofing Services Tampa with the appraiser’s wording and your closing date, and we’ll get a roofer out who aims the fix, and the write-up, straight at that wording instead of describing the roof in general terms.
 On a VA loan, the appraiser checks the roof of a house like this against VA’s minimum property requirements.
What VA’s roof rule says, and what it leaves out
VA’s property standards live in chapter 12 of its Lenders Handbook (VA Pamphlet 26-7), where Roof Covering is its own topic. Federal rule 38 CFR 36.4351 ties a loan’s eligibility for the VA guaranty to the property meeting those standards. VA’s own MPR checklist puts the roof requirement in two lines: the roof covering must prevent entrance of moisture, and it must provide reasonable future utility, durability and economy of maintenance.
That checklist wording doesn’t set:
- a roof age limit
- a minimum number of years of remaining life
- a limit on the number of shingle layers
The question VA publishes is whether the roof keeps water out now and will keep doing it for a reasonable time without constant repair. In practice that reaches things like missing or broken roofing, signs of an active leak inside, or a covering so worn it can’t be expected to last. If your lender works from a more specific standard, that wording is what the fix has to answer, so read it to us.
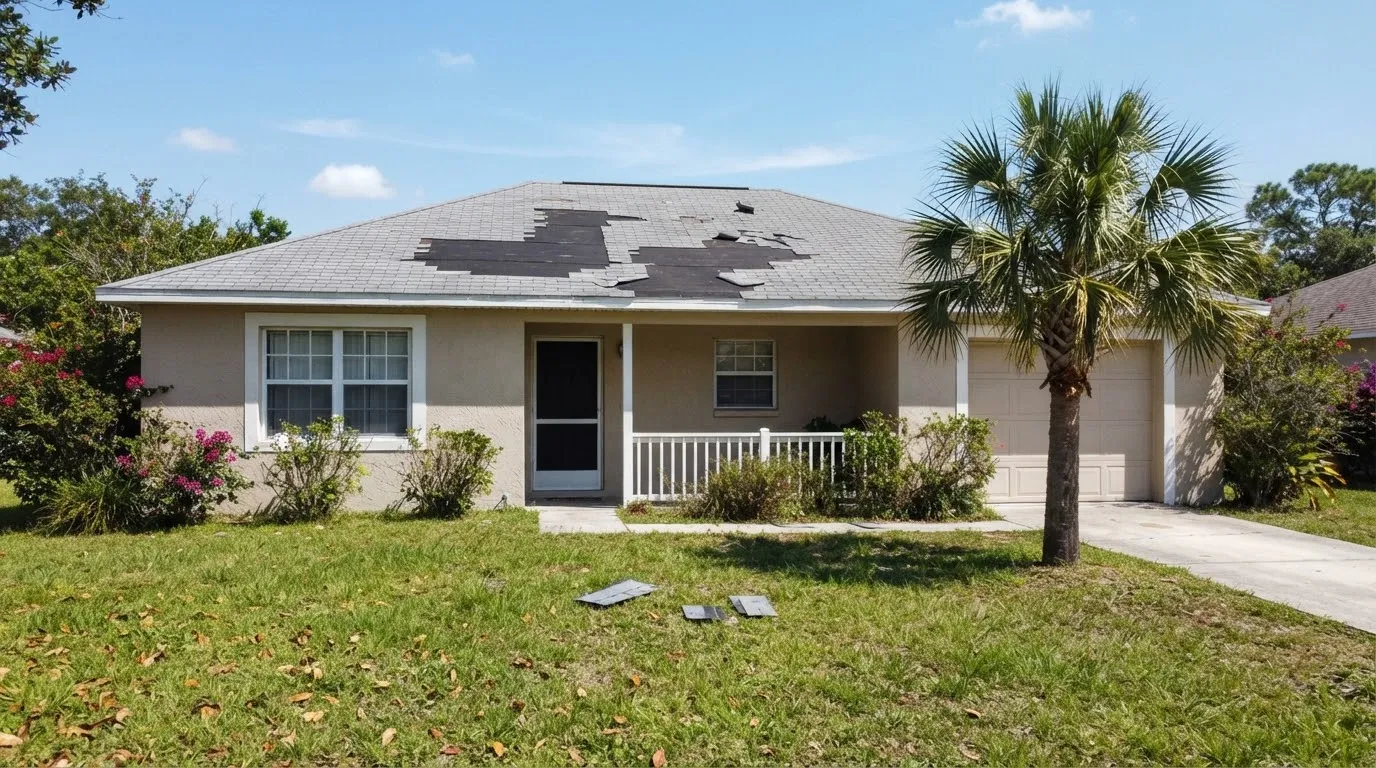 Missing or broken roofing is the kind of condition that lands on the repair list.
How a roof problem shows up on the Notice of Value
When the appraisal is complete, you get a Notice of Value (NOV). According to VA’s buyer’s guide, it lists the estimated value, comparable sales, the floor layout, photographs, and a list of items requiring repair to meet the minimum property requirements. A roof condition lands on that list.
The exact roof item decides the job. A condition asking for a leak to be fixed calls for a different visit, and different paperwork, than one asking a roofer to inspect the roof and state its remaining life. Read it to us word for word and the visit gets set up for the one you have.
Clearing the roof item before closing
What clears it. This varies by lender and by the condition. Depending on the lender, that can be a signed statement from the roofer, photos, the appraiser coming back to look, or some mix. Your roofer’s write-up quotes the condition in the appraiser’s own words and backs it with photos, so it fits whichever the lender asks for.
Permits and timing. A re-roof needs a building permit, and some repairs do too, depending on who issues permits for the address and how big the job is. Your roofer pulls it, and the final inspection is part of what proves the work was done, so it gets built into the schedule ahead of closing. Roof permits in Tampa and Hillsborough County covers the offices and the inspections.
What goes in your roofer’s write-up
A write-up that clears a roof item has:
- the appraiser’s condition, quoted word for word from the NOV
- what was done: repair or full replacement, the materials, and the area of roof involved
- the property address and the dates of the work
- a plain statement on the roof covering’s condition now, including whether it keeps water out, plus an estimate of remaining useful life in years if the lender asks for one
- before and after photos of each slope
- the roofer’s name, company and license number
- the permit number and final inspection date, when there was a permit
Where part of the roof can’t be walked or seen well, as with some tile and low-slope sections, the write-up says how each part was checked: from a ladder, from the attic, or on the roof.
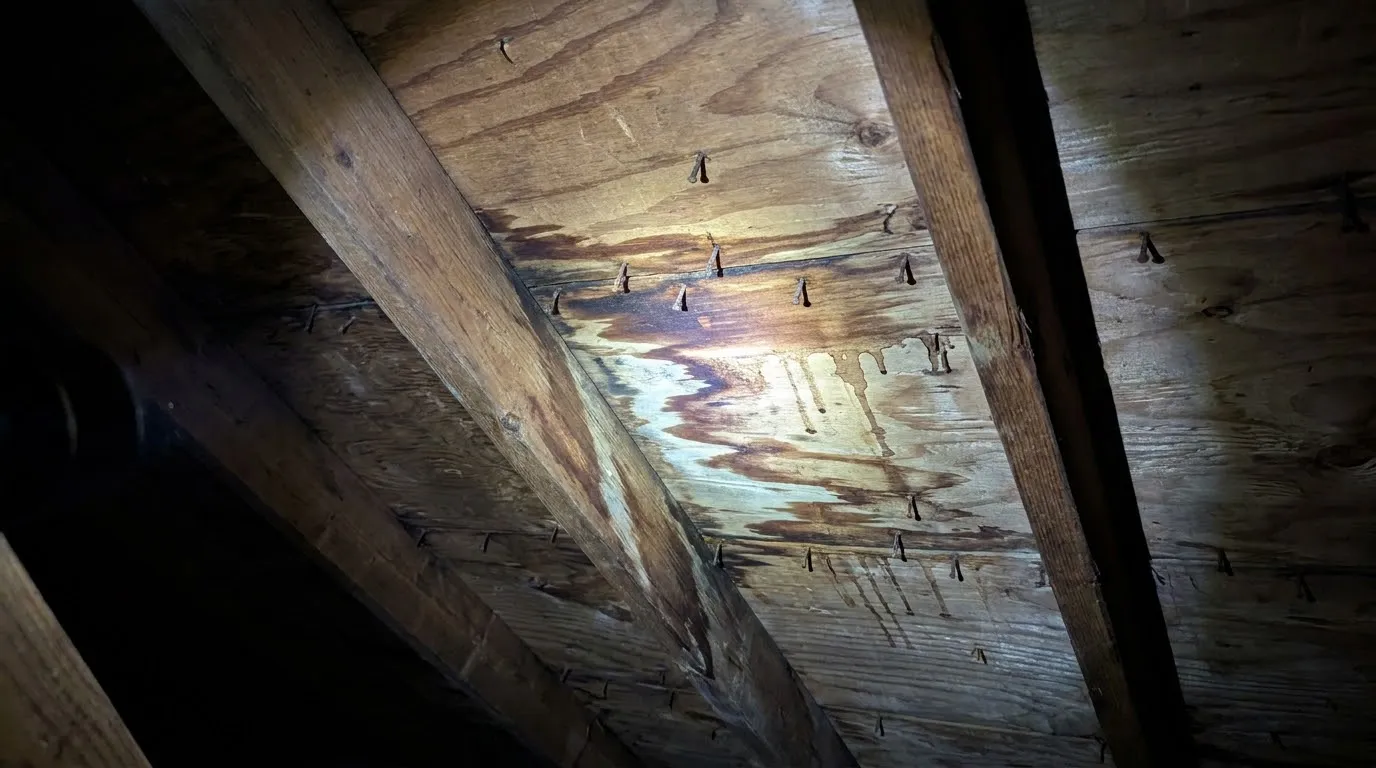 Where part of a roof can’t be walked, the attic is one place a roofer can check it from.
FHA’s roof rule, for comparison
FHA loans run on HUD Handbook 4000.1, and its roof wording goes further than VA’s. HUD’s handbook tells the appraiser to flag a roof covering that doesn’t keep moisture out, doesn’t provide reasonable future utility, durability and economy of maintenance, or doesn’t have at least two years of remaining physical life. With less than two years left, the appraisal is made subject to inspection by a professional roofer. If the appraiser can’t see the roof, they have to say why and report what the underside, the attic and the ceilings show.
That two-year line may not last. A September 2026 HUD draft that rewrites FHA’s property requirements keeps the moisture test and drops the remaining-life language. It’s a draft, not the rule, so the current handbook still governs.
| VA | FHA | |
|---|---|---|
| Keeps moisture out | Required | Required |
| Remaining life | No number in the MPR wording | At least two years (draft would drop it) |
| What a short roof triggers | A repair item on the Notice of Value | Appraisal subject to a professional roofer’s inspection |
| Roof can’t be seen | Not spelled out in the MPR checklist wording | Appraiser reports on the underside, attic and ceilings |
The Florida roof check that comes after the appraisal
Passing the appraisal isn’t the last time the roof gets judged. VA’s buyer’s guide notes that homeowners insurance is required for every mortgage, and in Florida the insurer has its own roof questions: how old it is, how much life it has left, and on older homes, a 4-point inspection. An older roof that satisfies the appraiser can still hold up a policy. A licensed roofer can sign the insurer’s roof form as well, and the forms and age rules are laid out on the roof certification for insurance page. If the insurer is asking too, tell us when you call.