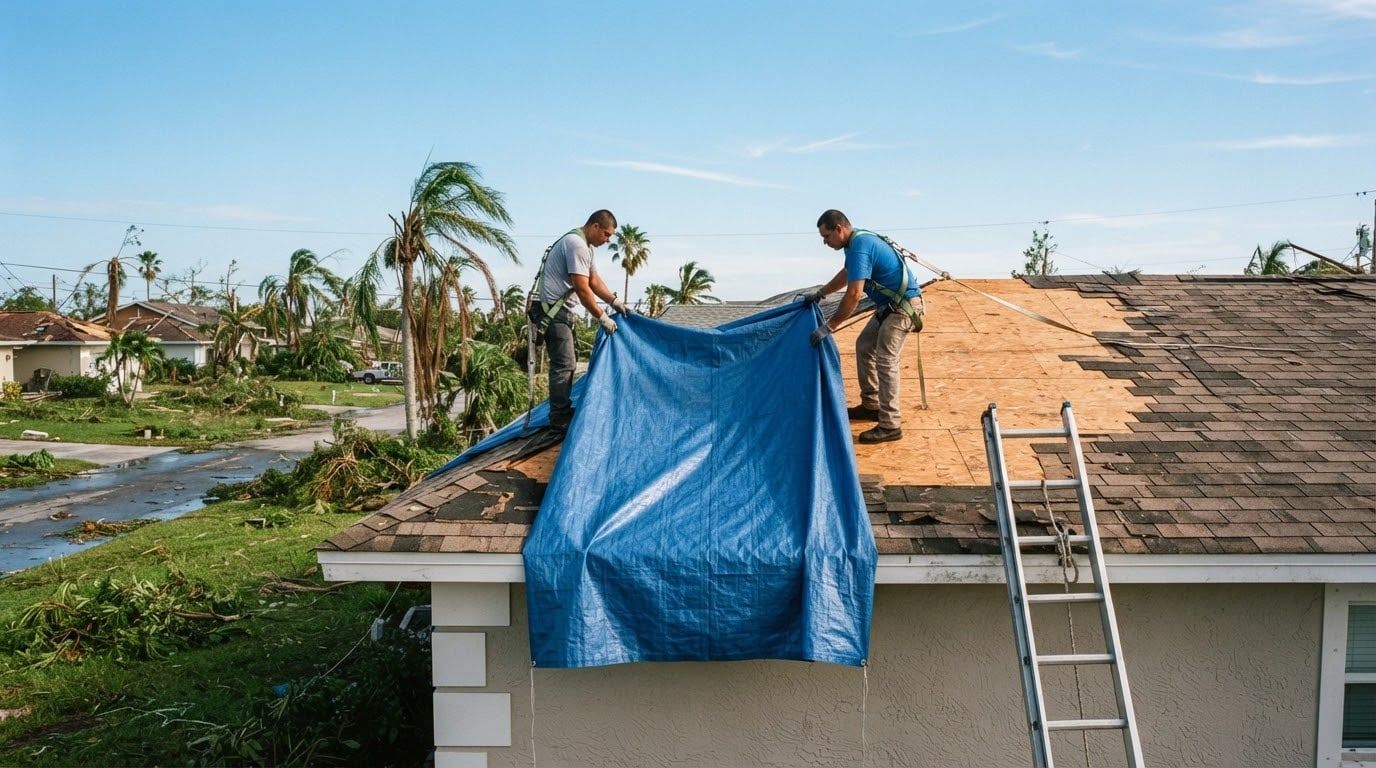
What to do first when a roof claim is denied
Find the reason in the denial letter, get the roof documented by a licensed roofer, and send that evidence back with a written request to reconsider, well inside Florida’s claim deadlines. The reason on the letter decides what the evidence has to show.
Call Roofing Services Tampa after a denied or underpaid roof claim anywhere in Hillsborough County, and we’ll get a licensed, insured roofer out to document the storm damage. You end up with dated photos, measurements and an itemized estimate you can set right beside the adjuster’s.
The Florida rules below are general and aren’t a reading of your policy.
Match the denial reason to the roof evidence
| The letter says | What the insurer decided | What your roofer documents |
|---|---|---|
| Wear and tear, age, deterioration | The damage came from the roof aging, not from a storm or other sudden event | Storm damage kept separate from old wear, slope by slope, with photos tied to the date of loss |
| Late notice | The claim came in after the policy or the statute allowed | The date of loss the report is based on, so it can be set against the deadlines below |
| Pre-existing or prior damage | The damage was there before this date of loss, or belongs to an older claim | Which damage is fresh and which is old, slope by slope. Older photos or inspection reports you already have help too |
| Below the deductible | Covered damage is worth less than your deductible | An itemized estimate in the same units the insurance estimate uses, so the two line up. A hurricane loss uses the separate hurricane deductible |
| Partial denial or a low payment | Some damage was accepted, some wasn’t, or the price came in low | The slopes, squares and decking the first estimate left out |
If the reason is something else, like a maintenance or installation exclusion, the approach is the same: the evidence goes to that one point. A letter that gives no reason, or no policy section, isn’t finished, and the insurer owes you both in writing.
What the insurer has to put in writing
Florida’s claims-handling statute, 627.70131, puts a lot on paper. Under it, the insurer must:
- give a reasonable written explanation of the basis in the policy for a denial or partial denial, tied to the facts or the law
- explain in writing why a payment came in lower than its own detailed estimate, when that happens
- send you a copy of any detailed estimate within 7 days after its adjuster writes one
- have any adjuster who inspects in person hand you their name and state adjuster license number
The detailed insurance estimate matters most. Have it with you when your roofer comes out. Your roofer’s report gets set against it line by line, and that comparison shows where the gap is, whether it’s the square count, the decking, or a slope left off.
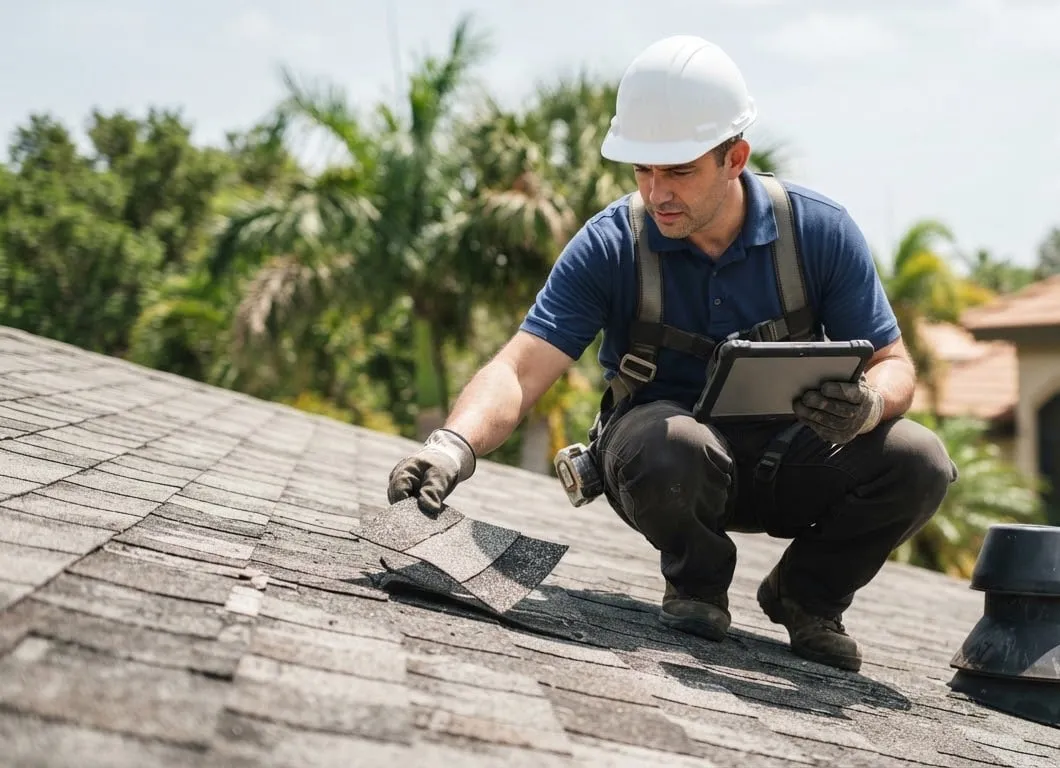 Your roofer’s report gets set against the insurance estimate, line by line.
Florida’s roof claim deadlines
A denial doesn’t pause anything. These clocks come from the 2026 statutes:
| Clock | How long | Statute |
|---|---|---|
| Notice of a new or reopened claim | 1 year after the date of loss | 627.70132 |
| Notice of a supplemental claim (more costs on a claim already made) | 18 months after the date of loss | 627.70132 |
| Insurer acknowledges your claim | 7 calendar days | 627.70131 |
| Insurer inspects in person, if it inspects | 30 days after your proof-of-loss statements | 627.70131 |
| Insurer pays or denies | 60 days after notice (up to 30 more days in a declared emergency, by state order) | 627.70131 |
The date of loss is set by the statute, not by when you found the leak. For a hurricane it’s the date the storm made landfall. For other windstorms, tornadoes and severe rain, it’s the date NOAA verifies the weather event.
Get the roof documented well inside these limits. Roof evidence fades fast: tarps go on, loose shingles get swept up, ceiling stains get painted over.
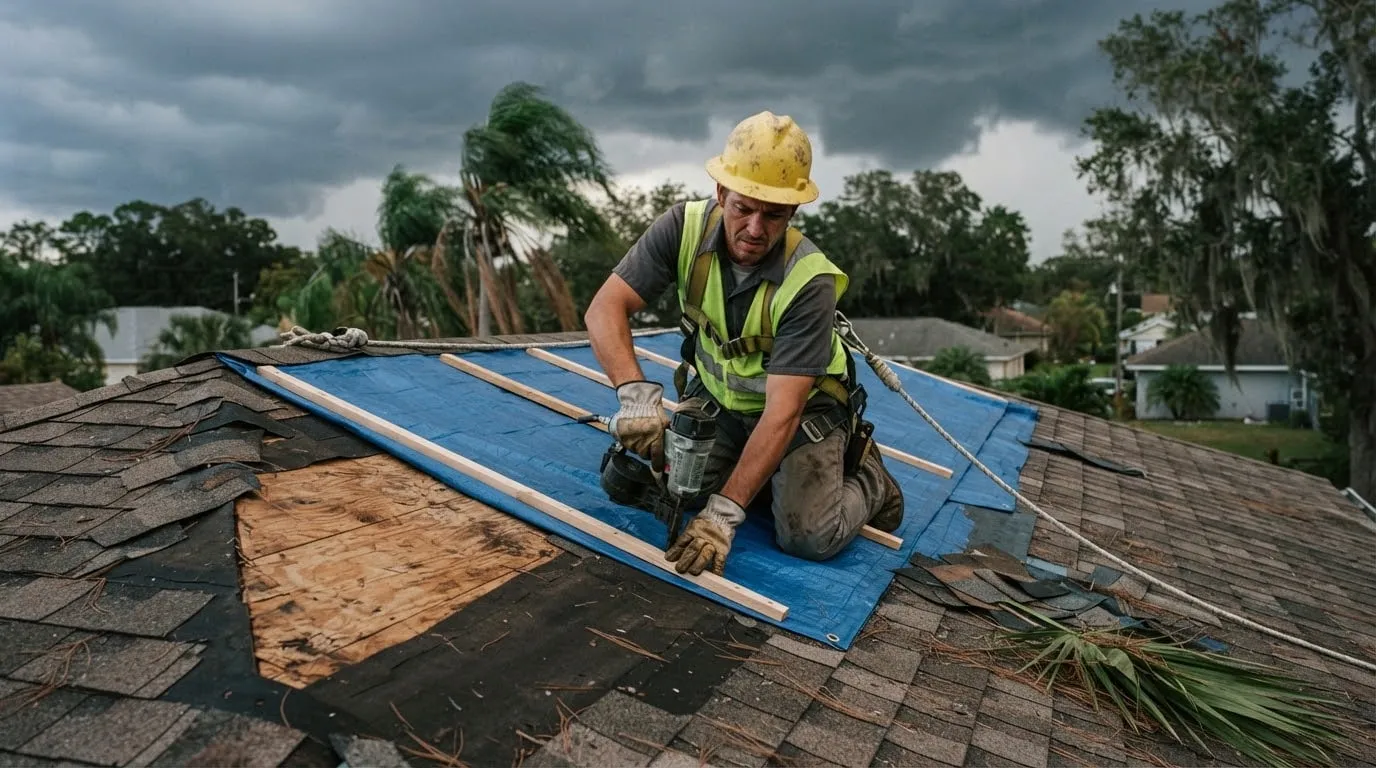 Tarps go on and debris gets cleared fast, which is why dated photos of the damage matter.
What goes in your roofer’s damage report
The report is built to sit beside the insurance estimate. On the visit, your roofer puts together:
- photos of every slope plus close-ups of each damaged area, dated, and the attic side where water came through
- the roof’s size in squares (one square is 100 square feet) and how much of it is damaged
- what the damage is and where, kept separate from normal wear
- the date of loss the report is based on, and the day your roofer was up on the roof
- an itemized repair or replacement estimate, in the units the insurance estimate uses
- your roofer’s name and Florida license number
Florida law keeps roofing contractors out of interpreting your policy or adjusting the claim, so the report sticks to what’s on the roof: the damage, the measurements and what it takes to fix. That’s what the insurer is weighing when it looks at a request to reconsider, or at a supplemental claim for damage the first estimate missed.
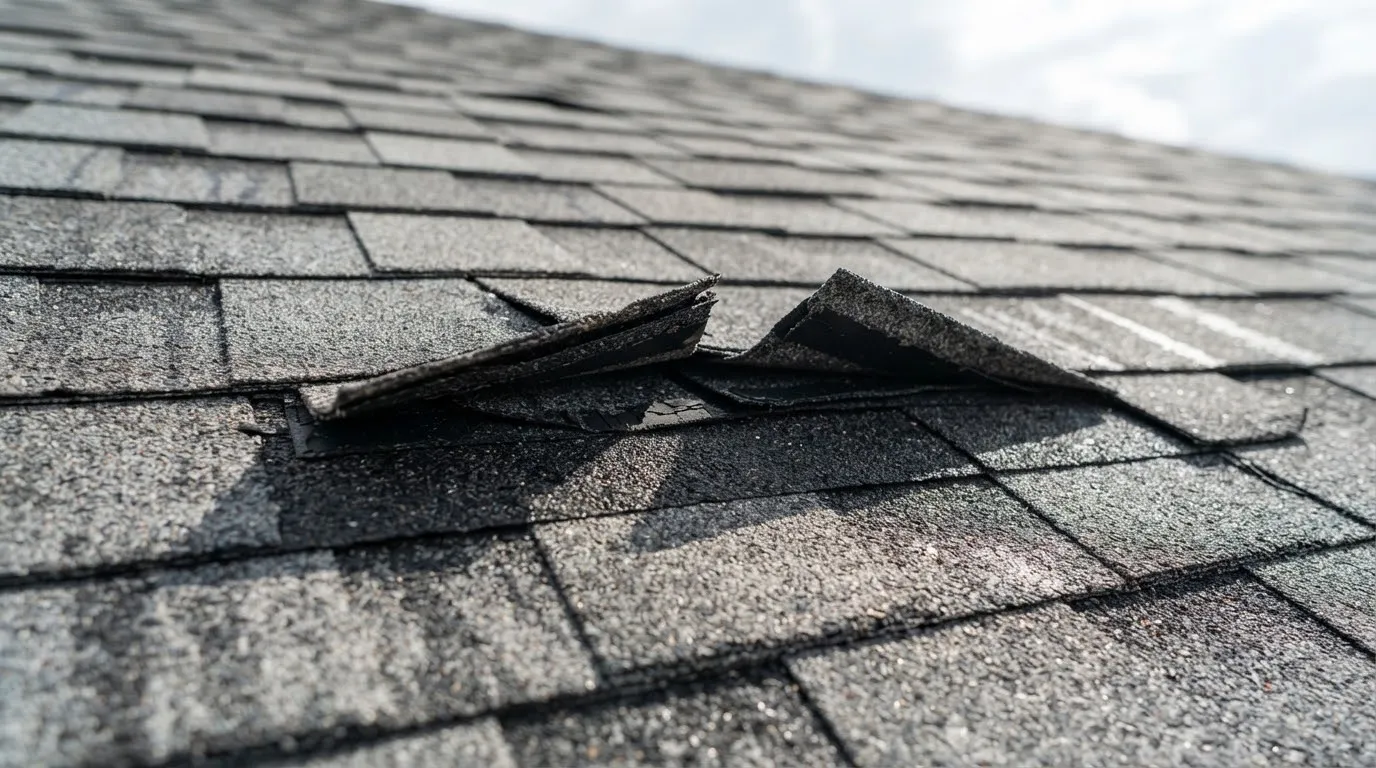 The report sticks to what’s on the roof: the damage, the measurements and what it takes to fix.
Water still coming in during the dispute
Don’t let the claim hold up the roof. If water is getting in while the denial gets sorted out, say so when you call, and the first job is stopping it. Emergency roof repair covers the tarp and temporary fix. Ask for photos of the damage before anything gets covered, so the evidence stays on record for the claim.