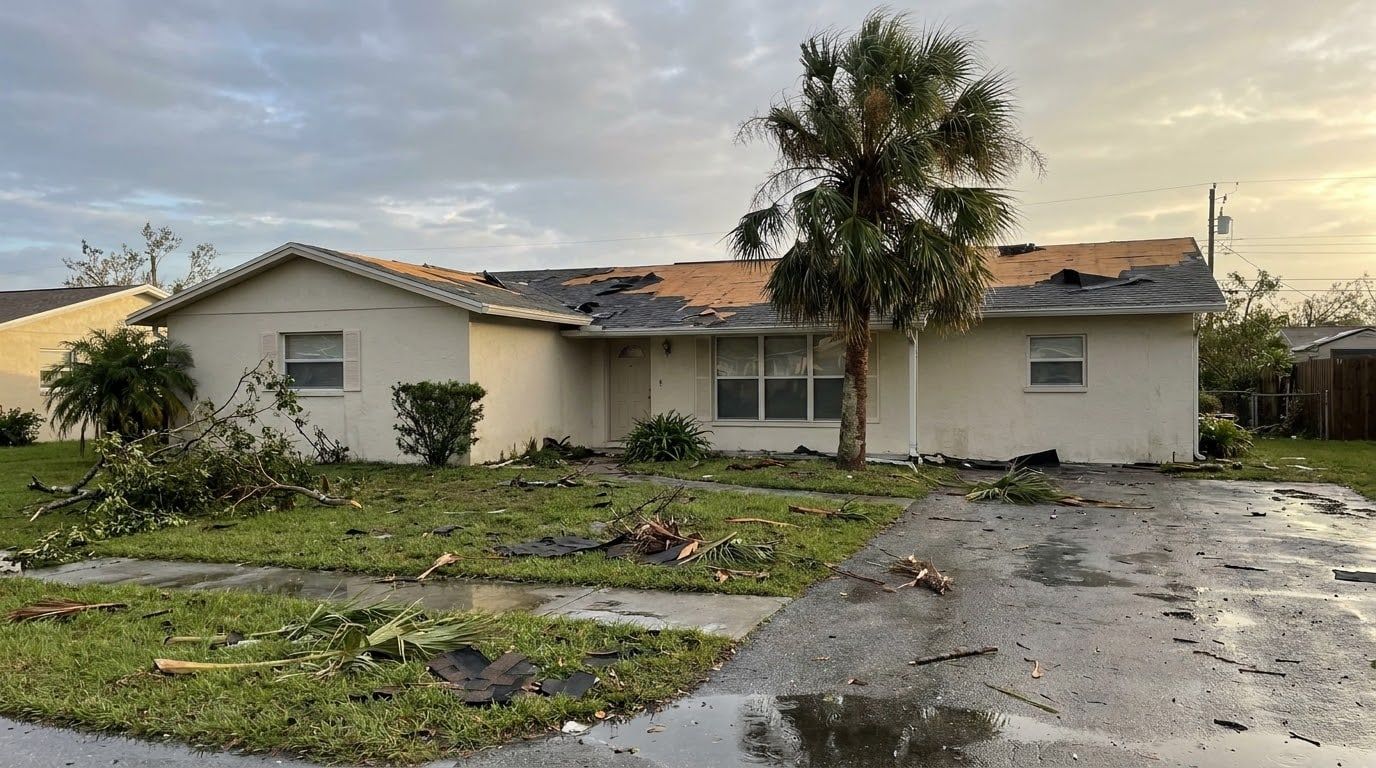
The short answer: one payment or two
Actual cash value (ACV) pays what the damaged roof was worth: the cost to replace it, minus depreciation for age and wear. Replacement cost value (RCV) pays to replace it with nothing taken off for age. On a Florida RCV claim, the insurer pays at least the ACV amount first, less the deductible, and the rest as the work gets done.
Roofing Services Tampa handles roof claim jobs in Tampa and across Hillsborough County. We’ll get a licensed, insured roofer out to write the itemized estimate, and once your roof is finished, you have the paperwork that shows what the work cost and that it got done. That paperwork is what an RCV claim runs on.
Which method applies to your roof is set by the policy, not by state law. It’s printed next to the dwelling coverage on the declarations page.
The math on a roof, with example numbers
These are round numbers picked to show the arithmetic. They aren’t a price for any real roof.
| Example claim | RCV policy | ACV policy |
|---|---|---|
| Replacement estimate the adjuster accepts | $20,000 | $20,000 |
| Depreciation taken for age and wear | $8,000 | $8,000 |
| Actual cash value | $12,000 | $12,000 |
| Deductible | $2,000 | $2,000 |
| First payment | $10,000 | $10,000 |
| Held-back depreciation, paid after the work | $8,000 | none |
| Total from the insurer | $18,000 | $10,000 |
| Left for you to cover | $2,000 | $10,000 |
The depreciation line is where the two policies split, and it’s figured line by line in the detailed insurance estimate. An older roof carries more of it. Have that estimate handy when your roofer comes out, so the two can be read side by side.
The deductible changes the picture too. A hurricane loss uses the separate hurricane deductible, which can be a percentage of the dwelling coverage. On an ACV payment, that can leave a small first check or none.
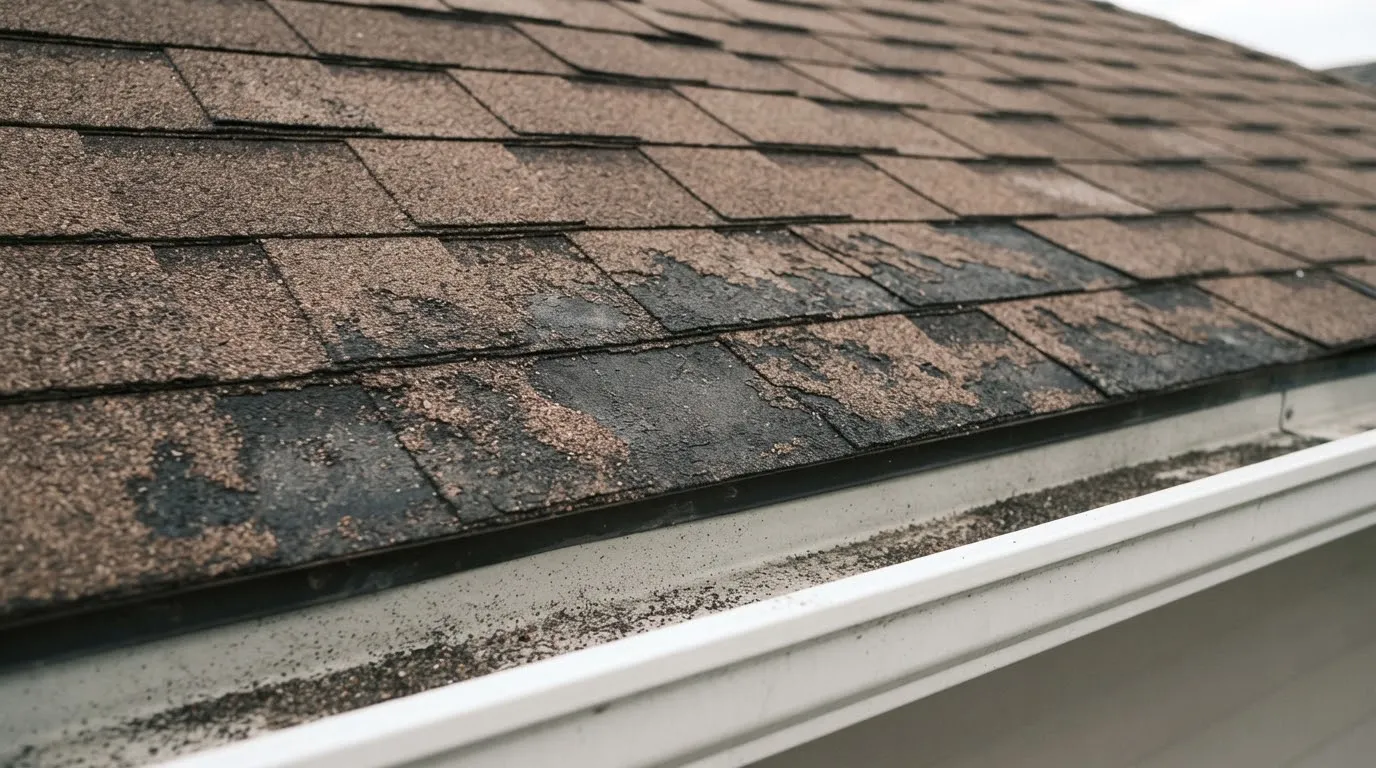 Wear like this on an older roof is what the depreciation line on an estimate reflects.
When the held-back depreciation gets paid
Florida’s homeowners statute, 627.7011, says the insurer must first pay at least the actual cash value of the loss, less the deductible, and then pay the remaining amounts “as work is performed and expenses are incurred.” The second payment follows the job, not the claim. On a total loss, the statute calls for full replacement cost with no holdback.
So the money that’s held back gets released by your roof job: the signed contract and the record that the work is done. If the job runs in stages, ask the insurer whether it will release the holdback in stages too.
Florida’s statutes don’t set a separate deadline for collecting the holdback. The general outer limit for a supplemental claim is 18 months after the date of loss (the full list is under roof claim deadlines), and a policy can add its own conditions. Don’t let a finished roof sit for months before the paperwork goes in.
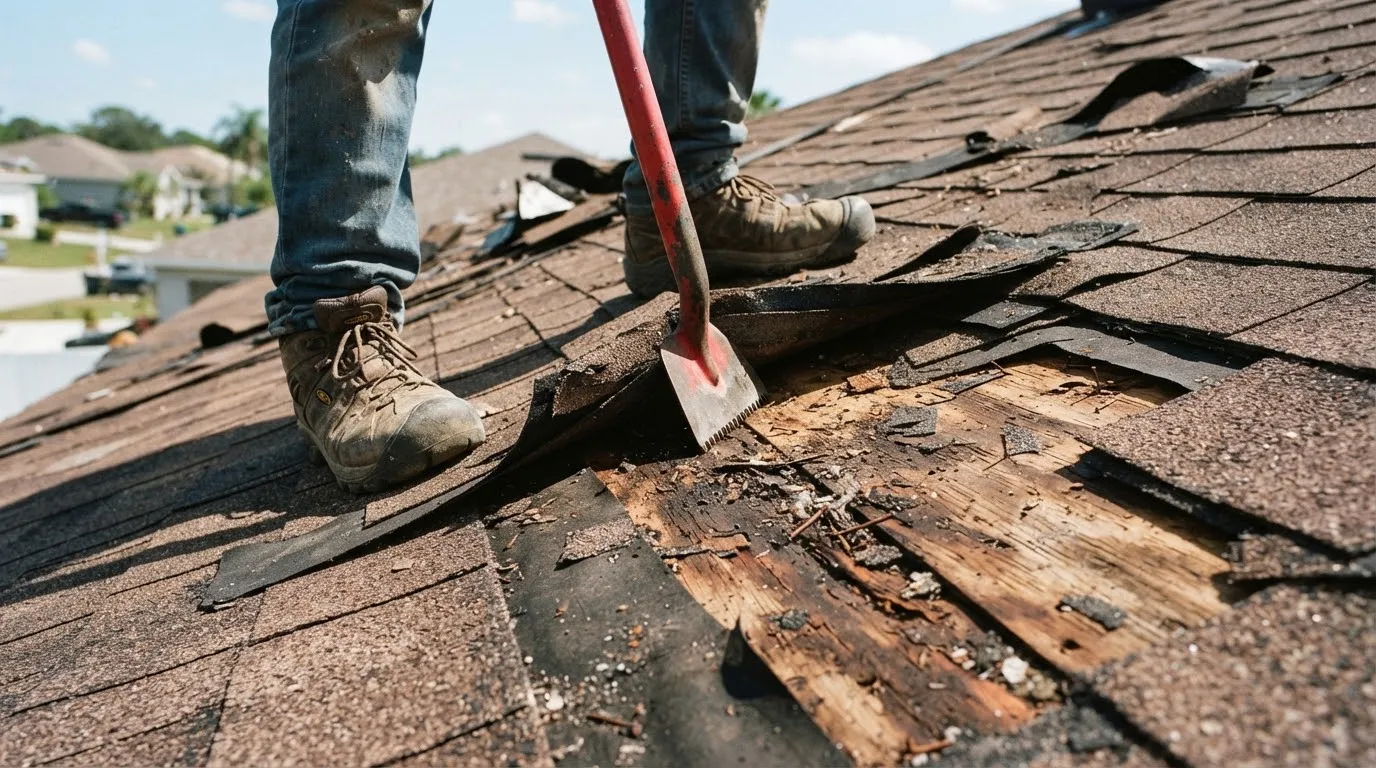 On an RCV claim, the held-back money follows the work, and the invoice for a tear-off like this is what releases it.
Florida’s separate roof deductible
Some Florida policies carry a roof deductible apart from the regular one. Section 627.701 caps it at the lower of two numbers: 2% of your dwelling coverage (Coverage A), or 50% of what it costs to replace the roof.
A worked example, again with made-up numbers: dwelling coverage of $300,000 makes 2% equal $6,000. A roof that costs $20,000 to replace makes 50% equal $10,000. The roof deductible can’t be more than the lower figure, $6,000.
It doesn’t apply to every roof claim. Under the statute it applies only to claims adjusted on a replacement cost basis, and not to:
- a total loss of the house
- roof damage from a hurricane
- a tree falling and puncturing the roof deck
- damage that needs repair to less than 50% of the roof
An insurer that uses one has to give you a rate credit for it and a warning page in large type. When the roof deductible applies, no other deductible can be taken on that loss, and the insurer may hold the roof payment to actual cash value until the roof deductible is shown as paid. That’s why an ACV-sized check can show up on an RCV policy.
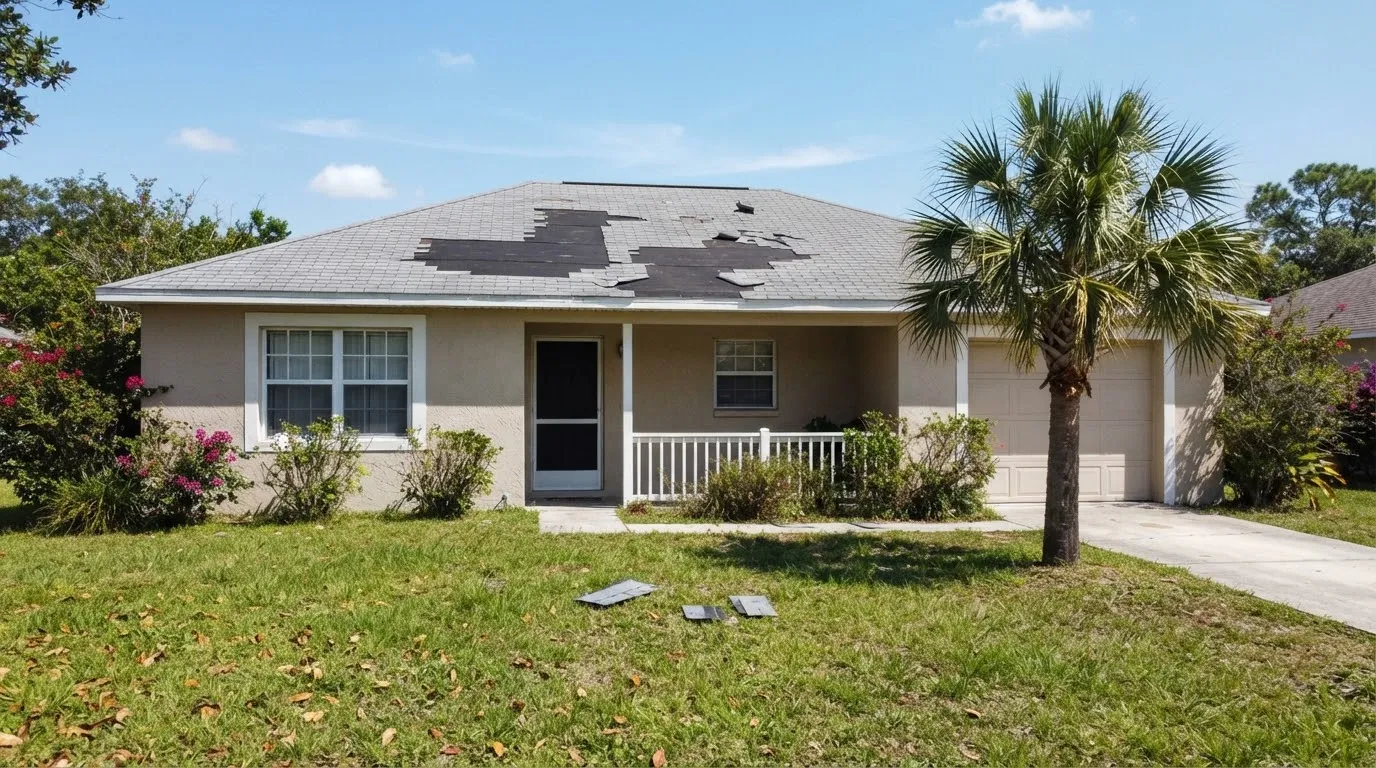 Missing shingles after a storm, the kind of damage your roofer writes up for the claim.
Is there a Florida roof payment schedule?
Not in state law. A schedule that paid older roofs a set share of replacement cost by material showed up in a 2021 bill draft, but the 2026 text of 627.7011 has nothing like it. If an insurer pays older roofs on a schedule, that comes from the policy itself, and it’s listed among the endorsements.
Where your policy shows ACV or RCV
The declarations page lists the dwelling coverage with “replacement cost” or “actual cash value” beside it, and the loss settlement section of the policy spells it out. Every deductible is listed there too: all other perils, hurricane, and a roof deductible if the policy has one. Endorsements with “roof”, “actual cash value” or “loss settlement” in the title can change how the roof is paid.
Law and ordinance coverage matters on an older house. Florida insurers have to offer replacement cost coverage with and without it, and the default is 25% of the dwelling limit unless it was rejected in writing, with a 50% option. A re-roof on an older house can include code upgrades on a re-roof, and that coverage is what applies to them.
Not sure which settlement method you have? Tell us when you call. Your roofer writes the estimate the same itemized way either way.
Paperwork from your roofer that lines up with the adjuster
Your roofer writes the job in the same units the insurance estimate uses, so the lines compare one to one:
- an itemized estimate in squares (one square is 100 square feet of roof), sheets of decking, and linear feet for drip edge and flashing
- separate lines for storm damage and for code items the building department requires
- the completion paperwork once the roof is done, which is what the holdback gets released against
- the permit and final inspection record when the job needs one
If the insurance estimate and your roofer’s come in far apart, the line items show where. For what goes into those numbers in the first place, see what drives roof replacement cost.